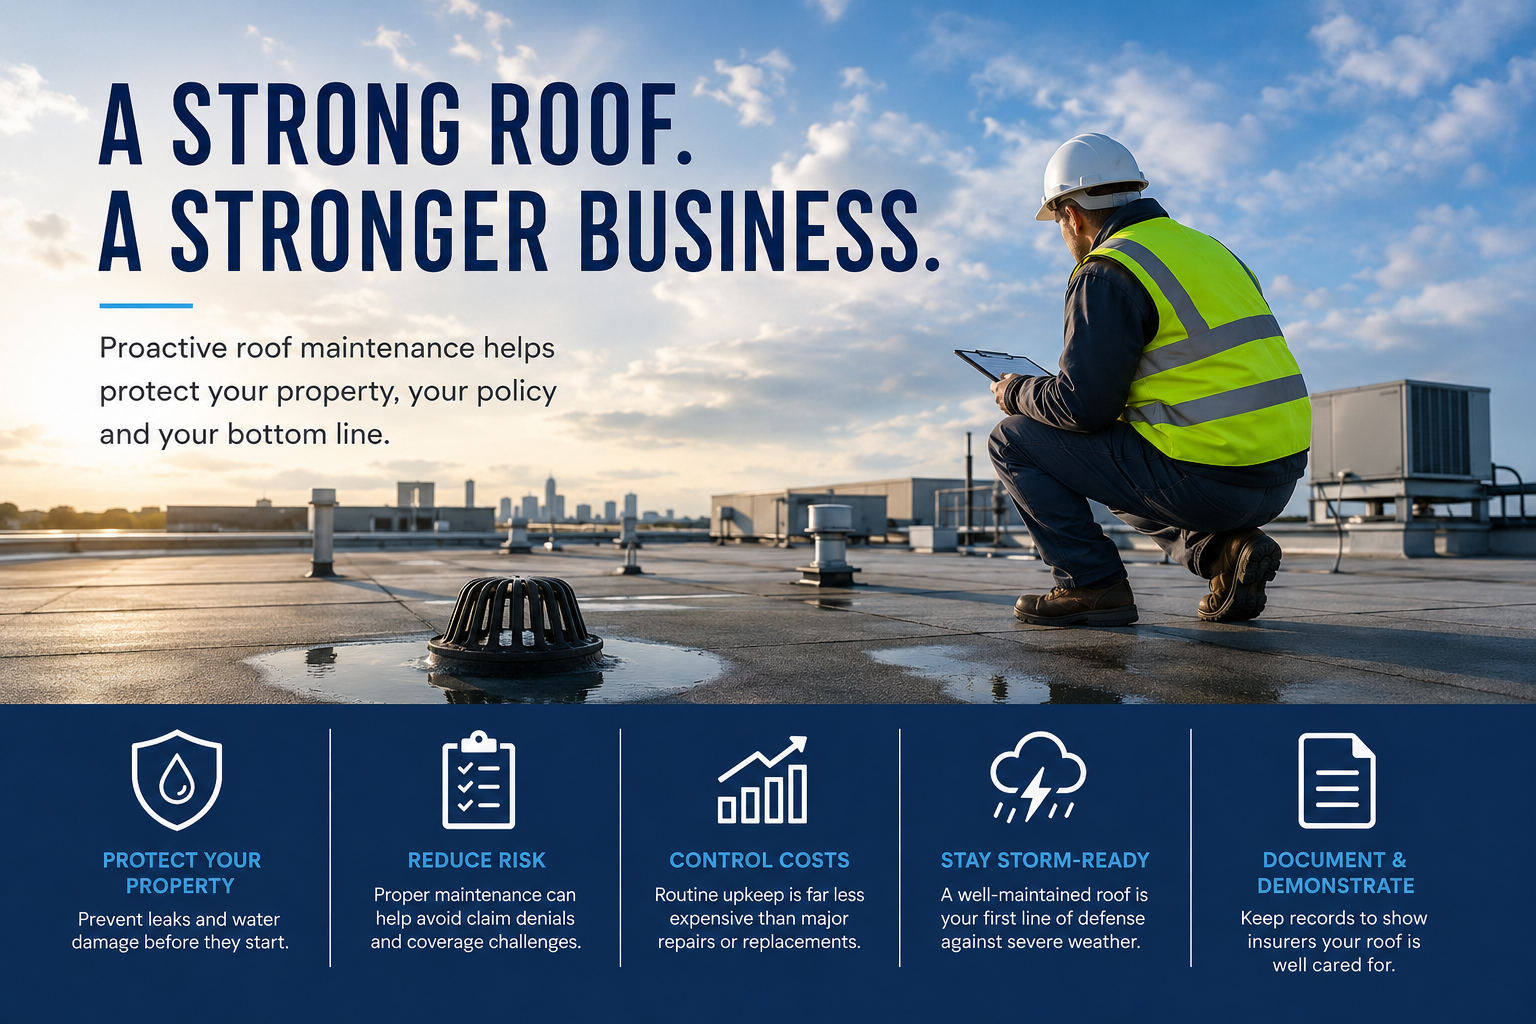
When people talk about building a successful business, they often say it starts with a strong foundation. While that’s certainly true, there’s another part of the building that deserves just as much attention: the roof!
A commercial roof is the first line of defense against rain, wind, hail, snow, and the elements. When it begins to fail, water can quickly find its way into the building, damaging ceilings, insulation, walls, flooring, electrical systems, equipment, inventory, and other valuable assets.
What starts as a minor roof issue can quickly become a major property loss—along with costly business interruption that impacts your ability to serve customers and generate revenue.
Delaying Roof Replacement Can Become an Expensive Gamble
As inflation continues to drive up construction and material costs, many property owners are trying to extend the life of aging roofing systems. Some rely on temporary repairs, while others hope that a future wind or hailstorm will result in an insurance-covered roof replacement.
Unfortunately, that strategy often backfires.
Commercial property insurance is designed to cover sudden and accidental damage—not years of deferred maintenance. If an insurer determines that deterioration, neglect, or inadequate maintenance contributed to the loss, portions of a claim may be reduced or denied based on policy exclusions.
In other words, waiting for a storm to “buy you a new roof” can leave you paying for much more than you expected.
It’s More Than Just the Roof Surface
Many business owners think roof maintenance simply means replacing missing shingles or repairing obvious damage. In reality, some of the most expensive losses begin with relatively small maintenance issues.
Common problem areas include:
-
Deteriorated sealants
-
Damaged flashing
-
Cracked pipe boots
-
Loose coping caps
-
Clogged roof drains
-
Ponding water
-
Failing HVAC curbs and penetrations
These issues often allow water to enter the building slowly over time. Hidden moisture can saturate insulation, rot roof decking, corrode fasteners, damage electrical systems, and create mold conditions long before a leak becomes visible inside the building.
By the time the damage is discovered, repair costs have often multiplied.
Insurance Companies Are Paying Closer Attention Than Ever
Roof-related losses remain among the most common and expensive commercial property claims. As a result, insurance companies have significantly increased their focus on roof condition during both underwriting and claims handling.
Today’s carriers frequently evaluate commercial roofs using:
-
High-resolution aerial imagery
-
Historical satellite photos
-
Drone inspections
-
Artificial intelligence (AI) image analysis
-
Infrared moisture detection
-
Weather history and analytics
-
Roof age databases
-
Predictive risk modeling
Many property owners are surprised when an insurer requests repairs, increases deductibles, raises premiums, or even declines to renew coverage based on roof condition.
Waiting until renewal to think about the roof is often too late.
A Roof Maintenance Program Protects More Than Your Building
A proactive maintenance plan isn’t just good building management—it’s good risk management.
An effective commercial roof maintenance program should include:
-
Annual professional roof inspections
-
Routine maintenance and timely repairs
-
Regular inspection and cleaning of roof drains
-
Documentation of all inspections and repairs
-
Post-storm inspections following significant weather events
-
A long-term replacement budget for aging roofing systems
Maintaining thorough records can also be valuable if an insurance claim ever arises by demonstrating that the roof has been properly cared for over time.
The Role Your Insurance Advisor Should Play
Insurance isn’t simply about purchasing a policy. It’s about identifying risks before they become losses.
One of the most valuable conversations an insurance advisor can have with a commercial property owner is about the condition of the roof. Planning for maintenance today can help avoid unexpected claim disputes, preserve insurability, reduce long-term ownership costs, and protect business operations when severe weather strikes.
Final Thoughts
Your roof protects nearly everything that keeps your business operating. Waiting until water is coming through the ceiling—or hoping the next storm pays for a replacement—is rarely a sound financial strategy.
Routine inspections, preventative maintenance, and long-term planning are far less expensive than major repairs, denied claims, or prolonged business interruption.
A well-maintained roof doesn’t just protect your building—it helps protect your business, your employees, and your future.

